 TICKWRIGHT
Tickwright — measure first.
35 of 36 lessons ready
About the channel
A claim about the market is taken apart and checked against numbers. The method is shown in full, including the places where it does not work.
Every video ends with something you can compute yourself: a formula, a checklist, or a chart you can mark up the same way. That is the only promise this channel makes. It does not promise income, it does not give signals, and it does not tell you what to buy.
Several findings in this course did not survive their own error bars. Those videos say so.
Narrated by synthesised speech.
Educational content only. Nothing here is financial advice.
How the course is built
Foundations
What a market actually is, what four numbers on a bar do and do not contain, the three orders you need, and what a trade costs before price has moved at all. Measured on real data, including the chart readings that turn out to be worth nothing.
Range
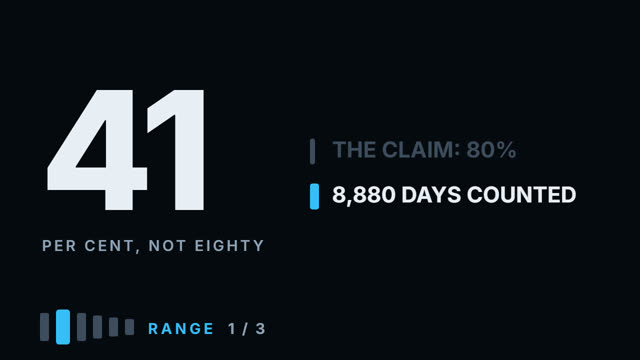
How far an instrument usually travels, how much room is left to the next level, and how much of the day is still ahead. The claim that price covers one ATR eighty per cent of the time is counted here: under the natural reading it comes out at 41 per cent.
Levels
Where a line on a chart comes from, what makes one worth trading, and how to mark up a blank chart by rule instead of by taste. Several popular criteria are counted here, and a level tested many times holds less often, not more.
Risk
Where the stop goes and why, how much room to leave between the level and your order, and the arithmetic that turns both into a position size. Also why a win rate on its own decides nothing, and what having something riding on the trade does to your decisions.
Setups
Bounce, breakout, false breakout, range and retest, on the same levels with the same accounting. Each set of rules is measured on its own, some survive the test and some do not, and the videos say plainly which is which.
System
Your own way of working: where to trade, what is worth looking at before the session opens, what belongs in a plan and in a journal, which of your statistics still hold when the history is cut in half, and where experienced traders genuinely disagree.
The course
Foundations
Who Actually Moves Price
Over 250 sessions Tesla travelled $3,754 and finished $7 from where it started. Ninety nine point eight per cent of everything that happened cancelled itself out. That number is what a market is. Two sides, broadly balanced, settling over and over — and a thin residue on top that does not arrive evenly. On Apple, the entire year's net move is covered by six days out of 249. And a third of all movement on that stock happens while the exchange is closed and nobody can trade at all. Everything here is measured: the calculation ships with the video.
not published yet
How to Read a Price Chart
A bar on a chart is four numbers: where the day opened, the highest it reached, the lowest, and where it closed. That is the entire contents. Everything else people read in it is added by the reader. Two of the most common readings were counted on nine thousand daily bars across six instruments. A close near the high — supposedly strong — was followed by a higher day 52.3% of the time, against a base rate of 52.6%. The hammer, 812 of them, gave 52.1% against 52.7% for every other bar: slightly worse than not looking at the chart at all. And four numbers cannot contain the order events happened in, which is not a limitation of your charting software — 38% of days finished on the opposite side of yesterday's close from where they opened. What does carry information is size: after a bar bigger than 1.5× the instrument's usual day the next session moves 0.69 of a daily range, after a quiet bar 0.19. Everything here is measured: the calculation ships with the video.
not published yet
Market, Limit, Stop - The Only Three Orders You Need
Your platform offers a dozen order types. You need three of them, and two of the three are the same thing wearing different clothes. Choosing between them is not a technical decision — it is a decision about what you are willing to pay with. And a stop order does not do what most people believe it does.
not published yet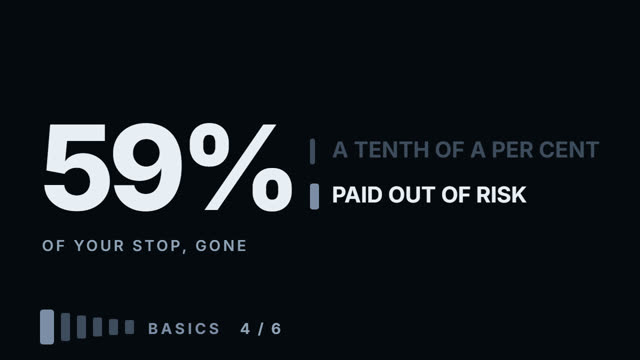
What a Trade Really Costs
Costs are quoted as a percentage of the amount you traded. They are paid out of your stop. Until you make that conversion, a tenth of a per cent looks like nothing. Made on one instrument it is a rounding error; made on another it eats more than half the risk before price has moved at all. The difference is not the venue being greedy — it is a percentage fee meeting a stop measured in the instrument's own movement. Everything here is measured: the calculation ships with the video.
not published yet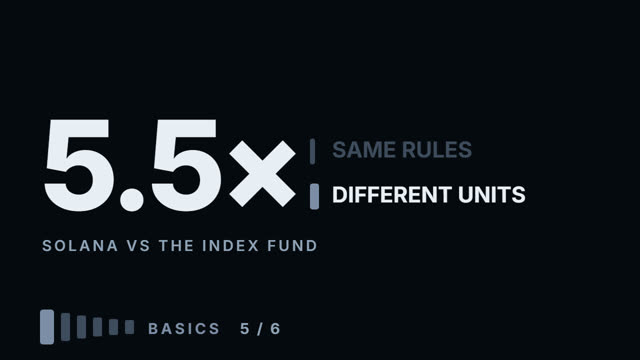
Stocks vs Crypto - What Changes, What Doesn't
Six instruments — three stocks and three coins — asked the same seven questions. Three answers came back identical. Four came back different, and one of those four is why accounts blow up when somebody moves from one market to the other. What carries across: the share of movement that cancels itself out (93–99.6% on stocks, 96–97% on crypto), the median body as a share of the daily range (40–49% on all six), and the one reading that survives measurement — bar size, which predicts two to three times the next-day movement on both markets. What does not carry: a typical Solana day is 5.5× a typical index fund day (4.7% of price against 0.85%); a third to 45% of stock movement happens while the exchange is shut, against zero on crypto; the worst overnight gap was 8.8%, and on crypto there is no overnight at all. One number that is quoted as a law of markets turns out to be a property of a period: the "next day higher" base rate was 52–55% on the stocks and under 50% on all three coins over the same year. Everything here is measured: the calculation ships with the video.
not published yet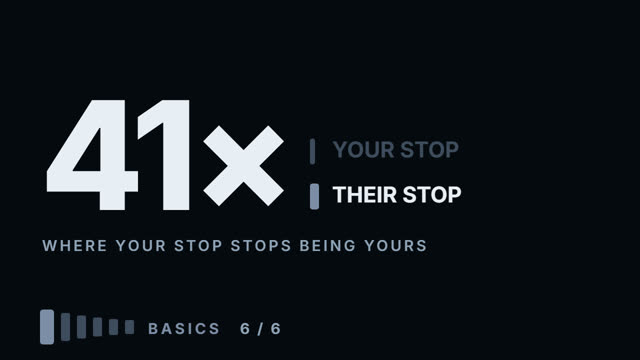
Leverage and Margin - How Accounts Blow Up
Leverage does not multiply your profit. It puts a second stop between you and the market — one you did not choose, cannot move, and that sits at a distance which has nothing to do with your idea. That distance is arithmetic: at 10× you are liquidated 9.5% against you, at 50× it is 1.5%, at 100× half a per cent. On Apple's last year a 1.5% fall from the open happened on 21% of days, and half a per cent on 63%. But the number that actually matters is the crossing point — the leverage at which liquidation becomes closer than your own stop. On Apple with a stop of one typical daily range that is 41×; on Solana it is 19×. Below it, leverage changes nothing at all: the same 248 trades on Apple, risk fixed at 1% of the account, returned 57.8% at 2×, at 5×, at 10× and at 20× — identical to the decimal. Above it the exchange decides instead of you: at 50× more than half the trades were liquidated before reaching the stop or the target, and the year returned 44% instead of 57.8%. Everything here is measured: the calculation ships with the video.
not published yetRange
How Far It Moves, and Why Two Measures Disagree
Eighty per cent of the time, an instrument travels one ATR. Every course repeats it, usually with a picture of a car and a full tank of fuel. I counted 8,880 days across six instruments to see what actually happens. The number is real. The sentence attached to it is not. Under the natural reading it comes out at 41 per cent, not 80 — and the 84 that does exist belongs to a different definition, one the same lesson gives and never connects to the number. The fuel tank turns out to be backwards as well.
not published yet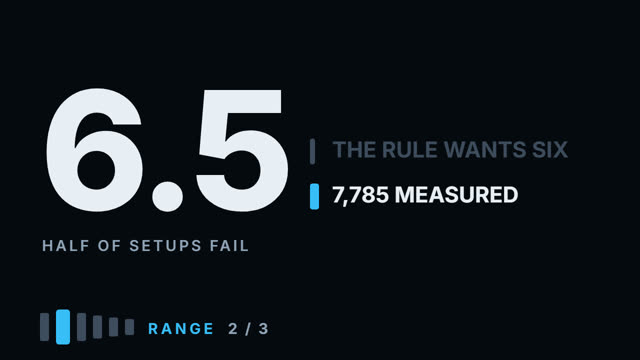
The Two Kinds of Room
Two questions decide whether an entry is worth taking: how far price can go from here, and how much of the day is left. Almost everyone checks one of them. Miss either and the setup fails for a reason that is never visible on the chart. It does not look like a bad read — it looks like bad luck. Both questions have numbers behind them, and both numbers were measured: 1,987 level crossings across six instruments and eight years.
not published yet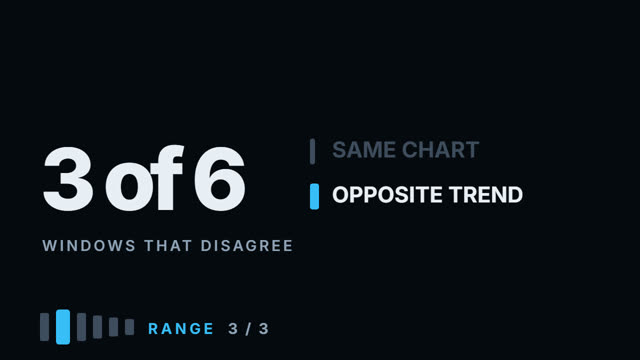
Measuring a Channel
Draw a channel on any chart and it will look right. That is the problem: two points make a line, and a chart of two thousand days offers thousands of pairs. So this video calculates the channel instead — a least-squares fit plus two standard deviations — and then measures the three things people expect from it. Price sits inside the band between 76% and 86% of the time, on every window from 20 days to 120: something that contains four days out of five describes where price has been, it cannot be a signal. A touch of the edge is followed by a move toward the middle 42.7% to 53.4% of the time, against base rates of 46% to 49% — a spread of −3.4 to +4.1 points, which is noise. And the channel is mostly your settings: one new bar moves a 20-day slope by up to 2.14 percentage points, and on three of the six instruments the 20, 60 and 120-day windows disagree about the direction outright. On Tesla, the same day, the same chart: +9.8% over 20 days, −7.2% over 60. A channel is not a forecast — it is a unit of measurement, and that is what it is good for. Everything here is measured: the calculation ships with the video.
not published yetLevels
What a Level Actually Is
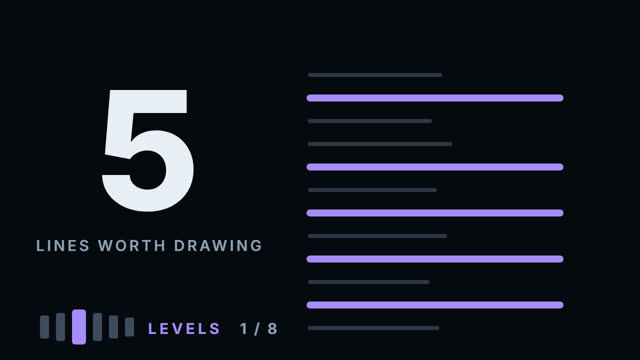
A line on a chart is not a feature of the market. It's a claim about one — and there are exactly three reasons a price level does anything at all. Once you have the mechanism, which lines to draw stops being a matter of taste. It also produces a conclusion most people find backwards: the best level on your chart is the most obvious one, not the cleverest one.
not published yet
Levels From Consolidation
Twenty candles that go nowhere. Everyone has a name for it — chop, a saw, a range — and everyone has advice, usually that a big move is coming. This is what the shape actually is, why it leaves the densest level on the chart, and how to measure it instead of squinting at it. Then the part I did not expect: I counted the claim that a strong move follows a consolidation, across 1,074 windows and six instruments. It is not there.
not published yet
Levels From Gaps
There is a hole in the chart: yesterday's close, this morning's open, and no trades in between. The standard teaching names three prices on that hole and calls them very strong levels. This is what those three prices actually do, measured on 476 gaps across three instruments and eight years of daily bars. They do nothing. On the first return price goes through them as readily as it turns away, and a day that moved just as much without gapping does slightly better. But something else showed up in the counting, and it points the opposite way from the lesson.
not published yet
Levels From Turns and Wide-Range Bars
There are two places almost everybody draws a level: the extreme of a turn, and the edge of an unusually big bar. Both were measured here, and the answer is more interesting than yes or no. First, the problem that makes measurement necessary: turns and wide-bar edges come to about 60 candidate levels per 100 trading days, on every one of six instruments. More bases than days — so there is always a level nearby, and the question is only whether that particular line does anything. Against a random horizontal line, turns look excellent: about 15 points more bounces. But that comparison is dishonest, because a turn is an extreme and price arrives at it from one side only — it measures edge against middle. The honest control keeps the edge and removes only the precision: the same turn, moved half to one and a half daily ranges away. Against that, turns gain between −1.5 and +11.4 points, median +8.5 — a real effect with an enormous spread, which effectively vanished on Tesla and the index fund. Wide-bar edges are weaker: median +5.1. And 83–87% of turns get revisited within 120 days, which is why levels feel so much better than they measure. Everything here is measured: the calculation ships with the video.
not published yet
Origin and Confirmation
One clean touch and a sharp reaction is the weakest evidence a chart can offer. A level worth trading has two points: one that creates it, one that proves it. And the second one can only ever be recognised after the fact — which sounds like a limitation and is actually what makes the method honest.
not published yet
Ranking Levels - Which One Do You Trade
Sixty candidate levels per hundred days is not a plan, so you have to choose between them. This video measures the five criteria people choose by — and two of the most popular ones point the opposite way from what they promise. "A level tested many times is stronger" is the most consistent result in the whole calculation, and it is negative on all six instruments without exception: on Apple a first touch bounces 82.5% of the time, a third or later touch 70.4%. Median across six: −13.2 points. The mechanism is mechanical — a level holds because orders sit there, every touch consumes some of them, and the last touch before a break is also a touch. "The level everybody can see works better" is also wrong: measured as a 60-day extreme it bounced 7.6 points worse on Apple, 15 worse on Tesla, and a few points worse on two of the three coins. Round numbers gave −1.5, which is nothing. Age points the same way as testing and on all six instruments: an old level bounces 9.1 points less often than a fresh one, a real result the video treats as too uneven to rank on. One criterion worked in the useful direction: a level created by a wide bar, +6.5 points on the median and positive on all six. And combining the two most-taught criteria — visible and tested twice — produced levels that held 29.5 points less often than everything else, on samples of three to fifty levels an instrument. Everything here is measured: the calculation ships with the video.
not published yet
The Levels Everyone Sees
This video was planned as an explanation of why the levels everybody sees work better. Then the previous video measured that claim and it turned out to be false — so the question changed instead of the answer. If a visible level does not turn price around, what does it do? It gets broken cleanly. A poke through a visible level came back only 57.7% of the time on Apple, against 72.9% for an unremarkable one — fifteen points fewer false breaks, and the median across six instruments is −6.4. And when price does close beyond a visible level, it goes further: on a shared time window, the move afterwards is larger on all six instruments. So attention does not make a level hold; it makes it resolve. The mechanism is the same one from the foundations module — a level everybody sees is a level everybody has stops at, and filling stops pushes price the way it was already going. This video also contains a mistake I caught before publishing: the first version showed stocks and crypto behaving oppositely, until both were recounted on the same years and the split disappeared. Everything here is measured: the calculation ships with the video.
not published yet
Marking Up a Chart From Scratch
The last video of the levels module introduces nothing new. It takes what the previous three measured and applies it to a blank chart — Apple, 16 March 2026, with the next six months hidden until the end. And it ends with the rules failing in a way that turns out to be the most useful thing in the module. The markup starts with 198 candidates: 73 turns and 125 wide-bar edges in 250 days. Distance cuts it to 107, then each level is scored using numbers lifted directly from the earlier measurements — +8.5 for a turn, +3.5 for a wide-bar edge, +5.6 for a wide origin, −15 for a level already tested twice, −3 for a visible one. No weights were fitted here. That leaves five lines. Then the six months are revealed: three of the five were never reached at all, while the naive markup — the obvious extremes anybody would draw — was reached five times out of five. The measurements were not wrong; they all answered one question (given that price arrives, what happens next) and none answered the other (will price arrive at all). And the two pull against each other: a level is untested precisely because price has not been going there. Filtering for reachable first raises the reached rate from 40% to 90% and lowers the bounce rate from 75% to 60% — a trade, not a free improvement. Everything here is measured: the calculation ships with the video.
not published yetRisk
Where the Stop Goes (Not Below the Level)
Your stop got hit, and then price went exactly where you thought it would. The usual explanation is that the stop was too tight. It wasn't — it was answering the wrong question. There is one question that decides where a stop goes, and it produces an order of operations that most people run backwards. That's the part that costs money.
not published yet
The Noise Buffer
Your limit order sat exactly at the level. Price touched it to the tick, turned, and went where you said it would — without you. The fix is not to enter at market. The fix is a small distance between the level and your order, and that distance is calculated. This is the number promised in the order-types video and in the one on where the stop goes: how big the gap should be, and where it comes from.
not published yet
Position Size and the Three Limits
Two traders take the same trade — same level, same entry, same stop — and one ends the day down one percent while the other is down six. Nothing about the setup differed. Only the number of units, and neither of them worked that number out. Position size is an output, not an input. This is the arithmetic that produces it, and the two limits that protect you from a run of losses the arithmetic cannot see.
not published yet
Why a 40% Win Rate Can Still Lose Money
Your win rate says how often you were right. It says nothing about whether you made money — and most losing accounts have a perfectly ordinary win rate. This is the arithmetic that decides it, worked on a real trade history, in one line you can run on your own trades tonight.
not published yet
Same Setup, Crypto vs Stocks
One setup, built entirely from what this channel has already measured, run on three stocks and three coins over the same years. The plan was to show what changes in the arithmetic when a method crosses markets. Then the setup turned out to lose money on both — and how that was discovered is worth more than the comparison. The first version did not check the stop on the entry day at all; reproduced on today’s data, that mistake by itself turns the result positive: +0.05R per trade. The second counted the target on the entry day too — +0.20R — but a bar has four numbers and no order, and a target reached that day was probably reached before the touch. The third filled entries with a quarter-range tolerance even where price never arrived, and never checked which side price approached from, so a sale at "resistance" counted while price traded above it: +1.18R. Each of those three is now reproducible by a flag in the calculation, which is the only reason I can tell you what they were worth. With all of them removed the setup averages −0.18R per trade, and all twenty-four instrument-by-buffer combinations are negative, from −0.02R to −0.28R. Winners: 28–30% on stocks, 26–30% on crypto. What transfers across markets: the win rate, the sign, and the response to a wider stop. What does not: the stop in per cent of price (0.43% on the index fund, 2.86% on Solana — a 6.6-fold difference in position size at the same 1% risk), the trade count (59–63 a year on crypto against 35–42 on stocks), and the cost in R, which inside one market is set by how close the stop is — on stocks the index fund pays 0.115R a trade and Tesla 0.029R, four times less, at the same commission. Everything here is measured: the calculation ships with the video.
not published yet
Why You Trade Worse When You Need the Money
Two traders take the same setup — same instrument, same level, same stop. One has nothing riding on it. The other needs rent by Friday. They will not get the same result, and the reason is not discipline. It is that they are solving two different problems, and only one of them has a deadline attached.
not published yetSetups
Trading the Bounce
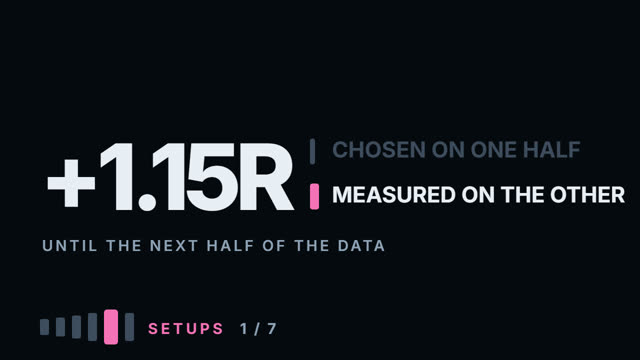
The previous video measured the bounce trade and it lost money on all six instruments — so this one cannot be "how to trade the bounce". Instead it takes the bounce apart: entry, stop and exit are three separate decisions, and each one is measured on its own, on the same signals. Entry at the touch averages −0.079R across every combination; waiting for the bar to close back and entering next morning averages −0.037R — four hundredths of an R, consistently, at the cost of half the signals. Stop width barely matters: half a daily range, one, and one and a half give −0.058, −0.059 and −0.065R, which is the same number three times. A fixed 2R target is the worst exit of the three at −0.124R, worse than a time exit at −0.035R and worse than a crude trail at −0.006R. One combination was impossible and said so clearly: entering at the touch with a stop behind the extreme of the touching bar returns exactly −1R on every one of 815 trades, because the extreme of a bar is only known once it closes. And then the part this video exists for: the best of the twenty-one combinations, chosen on the first half of the window, made +1.21R per trade over 188 trades — and the same rules on the second half returned −0.20R over 198. Similar samples, opposite sign, nothing about the market different between them. Two combinations do stay positive after costs over the whole window, and the best of those, +0.037R, loses 0.233R a trade on the half that had no say in choosing it. That gap is the size of the illusion created by choosing the best of twenty. Everything here is measured: the calculation ships with the video.
not published yet
Trading the Breakout
The levels module found that a visible level — a sixty day extreme — bounces worse than an unremarkable one, produces fewer false breaks, and carries price further once it goes through. Every one of those is bad news for a bounce and good news for a breakout, so the same feature should switch sign between the two trades. That is a prediction, not a hope, and this video tests it on the same levels, the same window and the same accounting as the bounce video before it. The prediction survives. Visible levels return +0.21R per trade against −0.04R for unremarkable ones, measured inside the same sample, so the direction of the window cannot explain the gap. Entering the day after the close beyond the level averages +0.04R while waiting for the retest averages −0.12R — the retest never comes when the breakout is real, so waiting leaves you holding the ones that failed. A tight stop wins, the reverse of the bounce. A wide breakout bar hurts: −0.13R against +0.09R for an ordinary one. And settings chosen on the first half of the window returned +0.12R on the second half, the test that destroyed the bounce video, passed here.
not published yet
Why False Breakouts Exist
Price broke the level, you took it, and twenty minutes later you were stopped out with price back inside the range. There is a mechanism behind that shape. It is ordinary, it is checkable, and it does not require anyone to be plotting against you — it rests on one fact about stop orders that almost nobody says out loud.
not published yet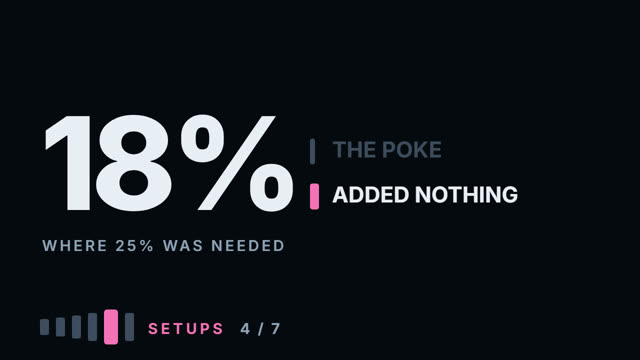
Trading the False Breakout
The previous video explained why false breakouts happen. This one checks whether that explanation is a trade. It is not — and the reason is more useful than the entry would have been. Two hundred false breakouts across six instruments. Sold the way it is taught, they return 18% at a target of three stops, where 25% is break even. The control group — days that came to the level and did not break it — returns exactly the same 18%. The poke through, the thing the whole setup is named after, adds nothing measurable. Everything here is measured: the calculation ships with the video.
not published yet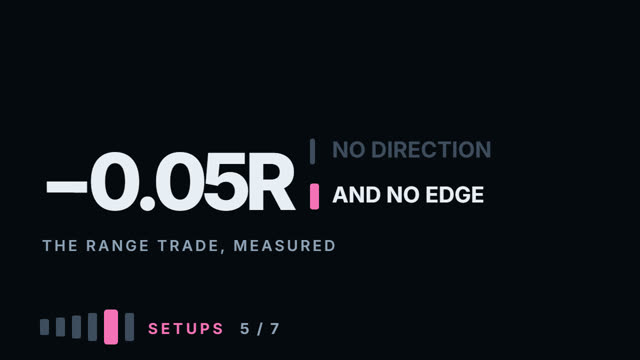
Range and Retest
The previous video measured the breakout as positive and then one split took half of it back: all of the edge was on the long side, in a window where six instruments went up. So the number was partly the market, not the setup. A range trade cannot have that problem — it buys the low and sells the high of the same band, and has no direction by construction. This video asks two things at once: does it work, and is that direction-neutrality real when you measure it instead of assuming it. It starts with the definition, because the first attempt was bad. "A band no wider than three daily ranges" produced a hundred and ten signals across six instruments — SPY had two. Loosening a threshold until the sample is big enough is fitting the definition to the answer, so the threshold now comes from the instrument itself: a range is when the twenty day band sits in the narrowest third of that instrument's own bands. Four hundred and twenty seven touches, nothing chosen by hand, and a control group made of the same touches when the band is in the widest third.
not published yet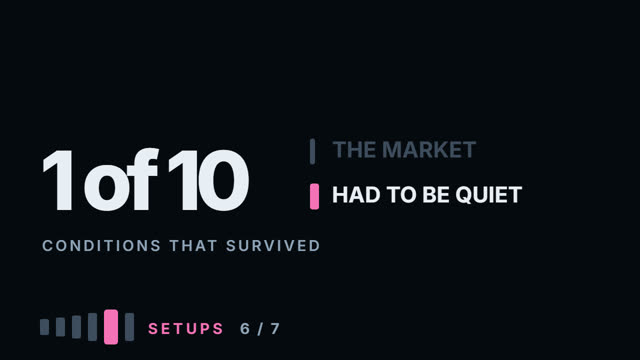
What Has to Be True Before a Breakout Works
The previous video measured the breakout, found three conditions on the level itself, and then one split showed that most of its edge was the direction of the window. So this one asks a harder question: of everything you can see before a breakout happens, what actually helps — in both directions? Both directions is the whole test. A condition that only improves upward breaks, in a window where everything went up, is not a condition; it is the window wearing a costume. Ten candidates are measured separately on upward and downward breaks, with trade rules taken from the previous video rather than chosen here: enter on the next open, stop half a daily range beyond the level, exit after ten days. The base with no condition at all is +0.17R upward on 331 trades and +0.01R downward on 293. That is the bar.
not published yet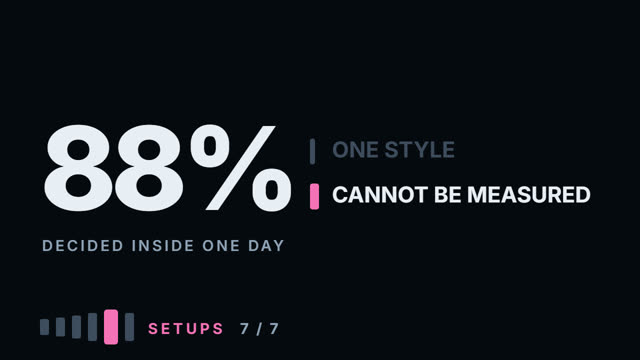
Three Ways to Trade the Same Level
The same event — price arriving at a level — can be traded three completely different ways, and people argue about which one is right. This video replaces the argument with a measurement: the same 792 touches, six instruments, two and a half years, and three sets of rules. No names attached, because what matters is the machinery. The fast way enters at the touch with half a daily range of stop and takes one stop of profit, out within two days. The middle way waits for the bar to close back off the level, stops a full range away, targets three stops. The slow way stops two ranges away and trails the exit. Start with what each way demands rather than what it returns. The fast way asks for a decision forty nine times a year per instrument; the other two, twenty five. Median time in position is one day, six days and three days — and that last one is the surprise, because a style built for thirty days exits in three the moment a trailing stop takes it out. Win rates are almost identical at 34, 34 and 39 percent. Take the single best trade out of each style and none of them changes, which is the first genuinely reassuring number in this series: no style here rests on one lucky day.
not published yetSystem
What's on the Screen Before the Session
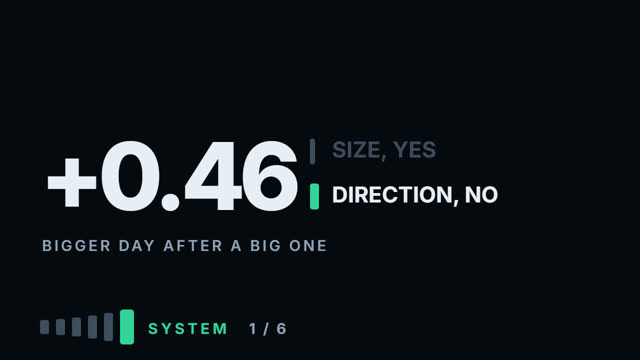
Before the market opens you can already see yesterday's bar, the gap, where price closed inside its recent range, how far it sits from its average. Every course treats that screen as preparation, and preparation is supposed to decide more than anything you do inside the session. This video measures what the screen can actually tell you, and the answer splits cleanly in two: a trading day has a size and a direction, and the pre-open screen answers exactly one of them. Size first. Measured as today's range in daily ranges of the instrument, so the numbers compare across Apple, Tesla, an index fund, Bitcoin, Ethereum and Solana. After a day that was bigger than usual, today is bigger too: on Apple the median range goes from 0.86 to 1.23, and the same measurement is positive on all six instruments, median +0.46 of a daily range. It is the largest and most consistent result in the video, and it survives the split — +0.42 on the first half of the window, +0.33 on the second. The gap is second and smaller, on the three instruments that actually close overnight. Where price sits in its twenty day band tells you nothing about size at all: median difference −0.01.
not published yet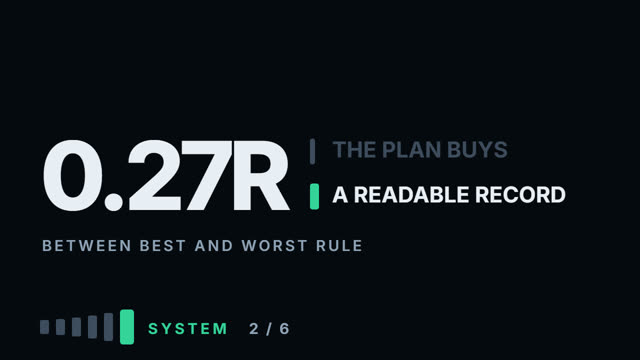
Writing a Trading Plan You'll Actually Follow
A trading plan is decisions made in advance. Everyone says it; nobody says what a decision made in advance is actually worth. This video tries to put a number on it, and the number does not survive the video — which turned out to be the more useful result. One signal, a touch of a level, and three decisions: where to enter, where the stop goes, how to get out. Two entries, three stops, four exits. Twenty four combinations, 817 touches, six instruments. The whole grid first. The worst of the twenty four combinations returns −0.19R per trade and the best returns +0.09R, a spread of 0.27R. That looks like the price of having no plan at all, and the obvious next question is which of the three decisions is the expensive one. Fix two, leave the third open, measure the spread: across the full window the stop gives 0.07, the exit 0.06, the entry 0.02. A clean order to write a plan in — until you check it on the two halves, where the order comes out entry, stop, exit and then entry, exit, stop. Three orderings from the same data. That is not a ranking; it is noise wearing one.
not published yet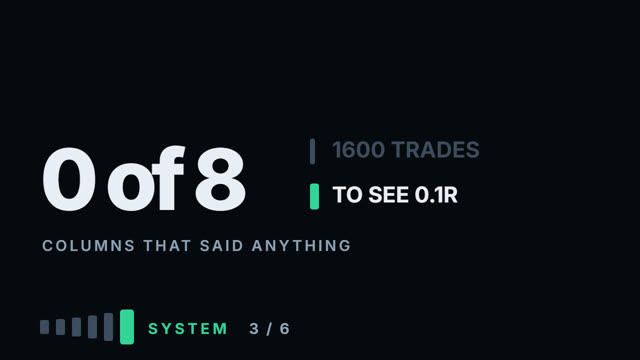
The Trade Journal - What to Log, What to Ignore
Every trading course tells you to keep a journal, and most hand you a template with twenty columns: entry, exit, setup, mood, news, sleep, confidence, market condition. The implication is that one day you will look back and one of those columns will explain everything. This video measures which columns can ever do that, at the number of trades you will actually have — which turns out to be the only question that matters. Two kinds of column get mixed together in those templates. Arithmetic — entry price, stop price, exit price, size, date — is the measuring stick, and without it you cannot compute a single number from the previous video. Features are everything else, kept in the hope that some day a difference shows up along one of them. Eight features were tested here on 385 trades of a setup this channel already measured, with one question each: does this column split the trades into two groups with genuinely different results? Instrument class: +0.1R, error ±0.15. Direction: +0.19R, error ±0.14 — the largest positive difference in the list, and it still does not clear the bar. A 60 day extreme: −0.26R, error ±0.18 — larger still, and closer to the bar than any of them. Quiet market beforehand: −0.1. Far from its average: +0.12. Yesterday was big: −0.08. Monday or Friday: −0.17. Level older than a month: +0.12. Eight columns, eight results, zero that clear two error bars.
not published yet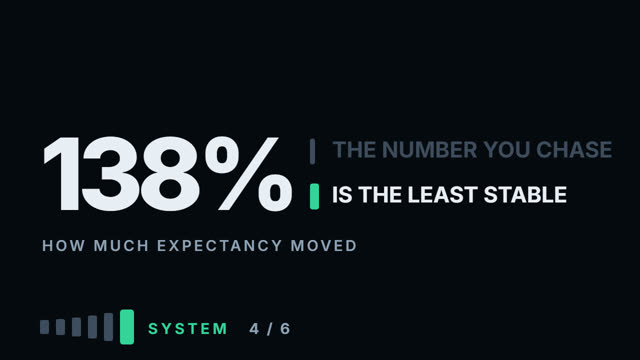
Reading Your Own Statistics
Every course ends the same way: keep a journal, compute your statistics, and the numbers will tell you whether your system works. Nobody tells you which of those numbers survive being measured twice. This video takes a real trade history — 413 trades from a setup this channel already measured — cuts it in half by time, and computes eight standard statistics on each half with the same rules. A number that comes out roughly the same on both halves is telling you about the method. A number that does not is telling you about the past, and only about the past. The sample sizes are deliberately realistic. Split in half, each instrument gives between 21 and 49 trades per half, which is roughly what a person actually has after a year or two of trading — not ten thousand. Every result below is measured at the size you will really be working with.
not published yet
Where Experienced Traders Disagree
Ask five experienced traders where the stop goes and you get five answers, delivered with complete confidence, at least two of them opposite. The usual explanation is temperament. This video tests a different one — maybe they disagree because the answer genuinely depends on the setup, right for a bounce and wrong for a breakout — and it is the last test this course runs. Two events on the same levels: a bounce, where price arrives at a level and you trade away from it, and a breakout, where price closes beyond a level and you trade through it. Three decisions with the same options for both — stop at half, one, or one and a half daily ranges; exit on a target, on time, or on a trail; enter immediately or the next morning. 766 bounce trades, 680 breakout trades, six instruments. One variant was thrown out before anything was measured: for the breakout, entering immediately means an order resting at the level, but the signal is the first close beyond it, so a resting order would also have filled on every day price touched the level and fell back — days that never entered the sample. That variant would have picked its good days afterwards, and the exclusion is in the calculation, not in a footnote.
not published yet